Range trading with financial spread betting means looking for price to move back from the edges of an established trading range. A trader may buy near support in the lower part of the range or sell near resistance in the upper part, expecting the boundary to hold long enough for an exit inside the range. The appeal is a relatively clear framework for planning entries, stops and targets. The difficulty is knowing when the apparent range has stopped being useful. A market can break out, drift into a trend or become too expensive to trade relative to the available movement. This guide explains how the approach works, who it may suit, its advantages and disadvantages, and how to assess it through hypothetical examples.
What is range trading in financial spread betting?
A trading range is an area within which price has repeatedly moved between identifiable upper and lower boundaries over a chosen period. The lower area is commonly described as support and the upper area as resistance. Range trading attempts to benefit from movement back towards the interior after price approaches one of those areas. It does not require every movement to travel from one boundary all the way to the other. A trader might target the midpoint, an intermediate obstacle or a price just before the opposite edge. Within financial spread betting strategies, range trading describes the reasoning behind a trade. A complete method still needs a definition of the range, an entry condition, position sizing and rules for abandoning the idea.
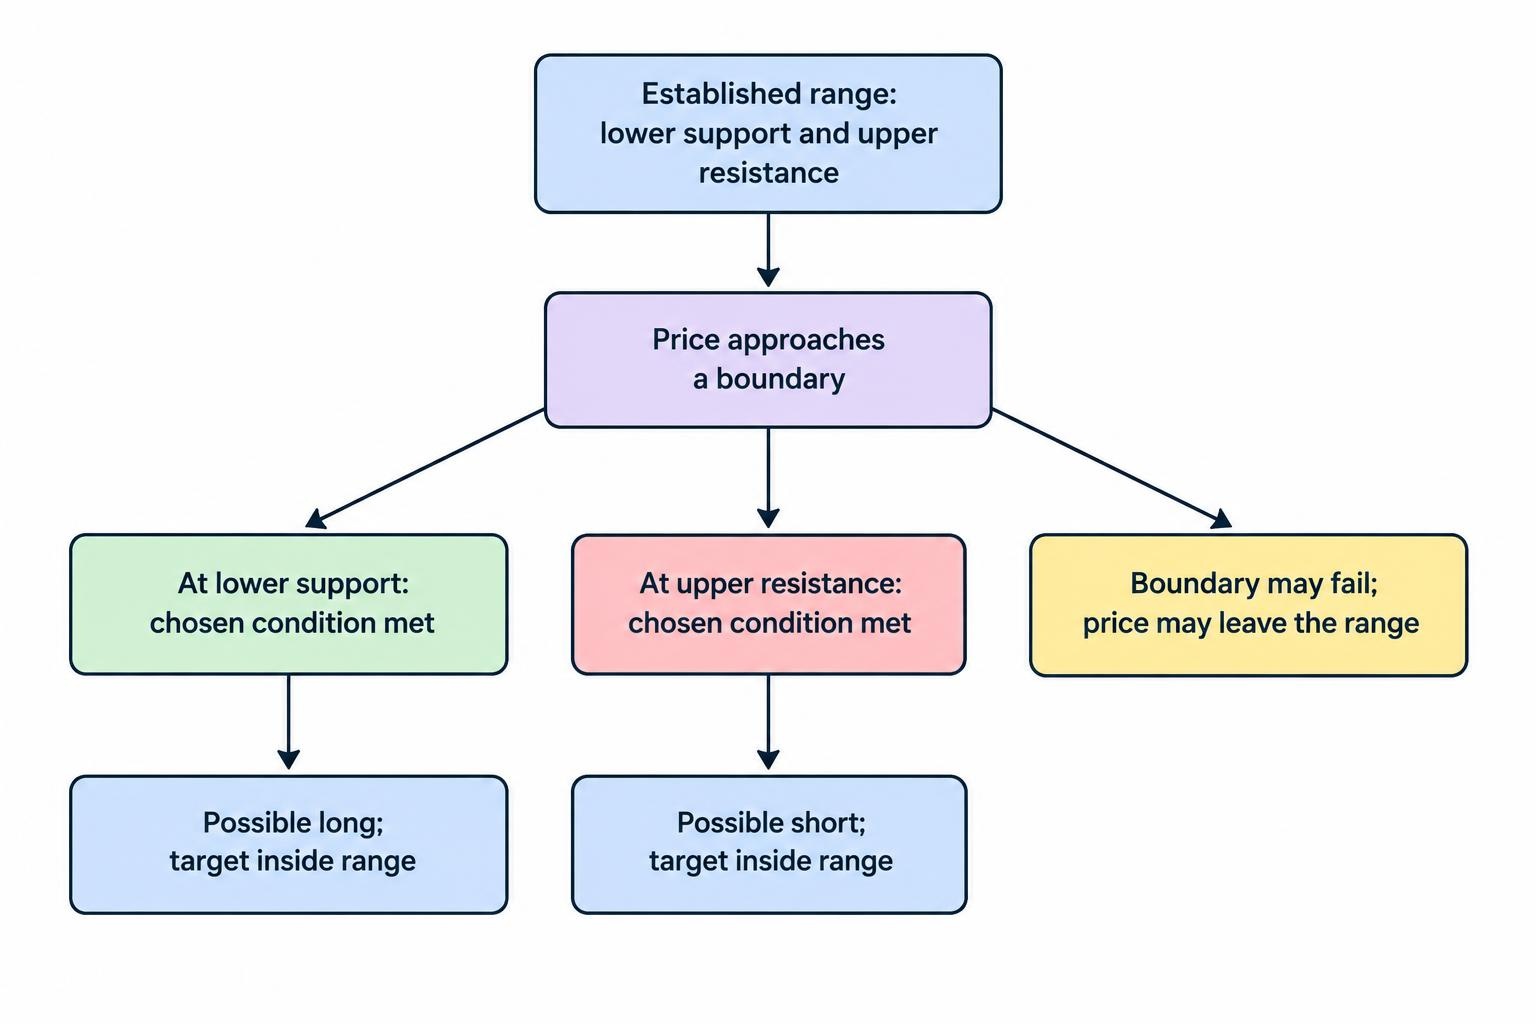
The spread bet provides exposure to that movement without ownership of the underlying asset. A long position opens at the buy price and closes at the sell price; a short position opens at the sell price and closes at the buy price. Price profit or loss equals the difference between the executed prices multiplied by the stake per point, with separate charges and adjustments included afterwards. The FCA includes spread betting within its supervision of contracts for difference and related products, which it describes as high risk and unsuitable for some retail consumers. A sideways market does not remove those risks. A range trade can lose through a breakout, a poor entry, excessive exposure, execution differences or costs that consume the expected return.
Range trading versus breakout trading and mean reversion
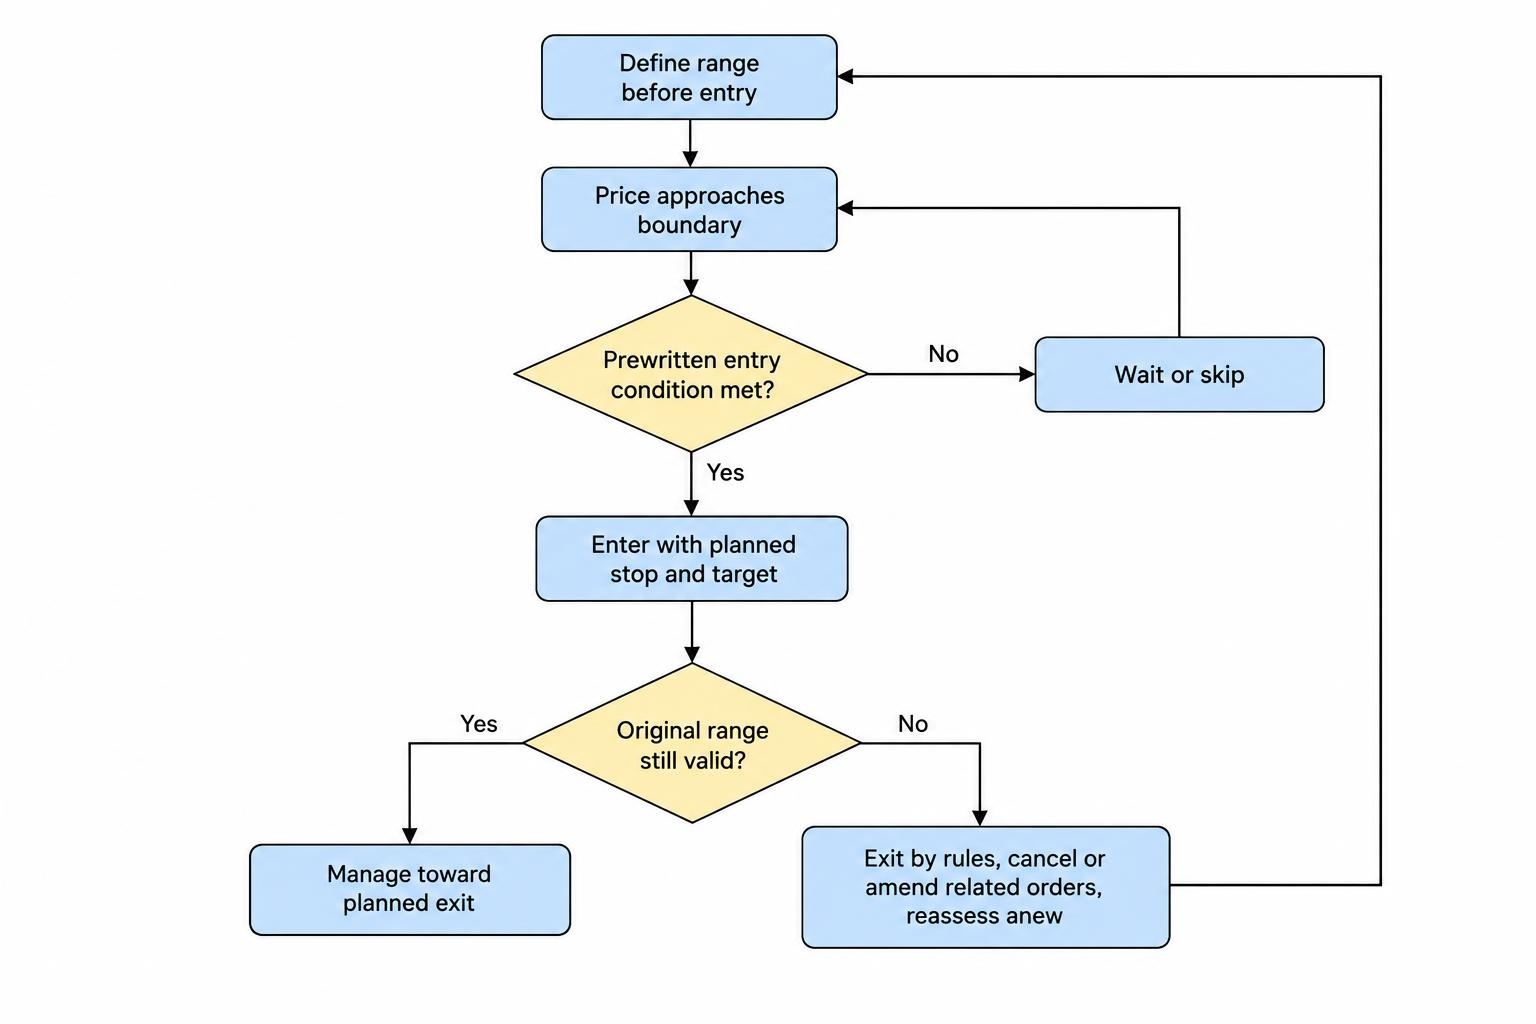
Range trading starts from the expectation that a boundary will hold for the purpose of the trade. Breakout trading starts from the expectation that a move beyond a boundary will continue. The same support area can therefore attract a range trader looking to buy a rejection and a breakout trader looking to sell a confirmed break. Neither interpretation is automatically correct. What matters is defining the conditions before entering and accepting the result when those conditions fail. A losing range position should not become a breakout strategy simply because price has moved outside the original area. Closing one idea and evaluating another requires a fresh decision, including new execution prices, risk calculations and consideration of the account’s existing losses.
Mean reversion is a broader concept that concerns movement back towards a chosen reference, such as an average price or a modelled relationship. A horizontal range is one possible setting for it, but the terms are not identical. Price can revert towards a moving average while continuing to trend, without remaining inside fixed boundaries. Range trading also differs from trend trading, which seeks continuation in an established direction. The timeframe matters: a market may range on a short chart while trending on a longer one. State which timeframe governs the setup and the exit. A short-term range inside a strong trend may require different expectations from a range that has contained the market across several sessions.
| Approach | Working expectation | Typical entry idea | Main failure to manage |
|---|---|---|---|
| Range trading | A defined boundary holds | Buy lower rejection or sell upper rejection | Price leaves the range and continues |
| Breakout trading | A boundary is crossed with continuation | Enter beyond support or resistance | Price returns inside the range |
| Trend trading | An established direction persists | Join a pullback or directional signal | The trend reverses or becomes choppy |
| Mean reversion | Price returns towards a selected reference | Enter after a defined deviation | The reference shifts or the deviation persists |
How to identify a trading range without hindsight
Start with a chart interval and observation period that match the intended holding time. Look for separated reactions around upper and lower areas, with movement between them, rather than drawing a box around any collection of candles. The boundaries should be recognisable before the proposed entry. A backtest that uses the eventual highest and lowest prices of the entire day to trade earlier in that day uses information unavailable at the time. Record when the range became valid and which observations established it. There is no universal number of touches that makes a range reliable. Closely clustered candles around one price are not necessarily separate tests, and historical reactions do not establish the probability that the next approach will reverse.
Treat support and resistance as areas rather than perfectly precise lines. Different participants can respond at slightly different prices, and ordinary price fluctuations can cross a nominal boundary without creating a sustained breakout. A useful method states the entry zone, the evidence required inside it and the point at which the trade no longer makes sense. It also defines how boundaries can be updated. Continually redrawing support lower as a long position loses money hides the failure of the original idea. If a new range develops, it should be identified through the same process used for the first one, rather than created solely to justify keeping an existing position open.
Is the range wide enough to trade?
A visible range may contain too little executable movement to justify a trade. Compare the available distance from the actual entry to the intended exit with the spread, expected slippage and any separate costs. The full distance between chart boundaries is rarely the amount available to the trader: a confirmed entry may occur inside the range, and a realistic target may sit before the opposite boundary. A narrow range can also require a stop outside the range that is large relative to the potential profit. Low volatility does not automatically mean low risk or good value. The relevant question is whether the method’s actual entries and exits leave enough return after costs to compensate for its losing trades.
For illustration, assume a long trade captures a 12-point favourable movement in the market’s midpoint, while a losing trade experiences an eight-point adverse midpoint movement. With a constant two-point spread and no other costs, actual buy-to-sell results would be a ten-point gain or a ten-point loss. The break-even win rate would be 50%. With a constant four-point spread, the same midpoint movements would produce an eight-point gain or a 12-point loss, raising that threshold to 60%. These figures are arithmetic assumptions, not expected performance. They demonstrate why spread changes matter in a contained market. If the recorded results already use actual buy and sell fills, the spread is already included and must not be deducted a second time.
Who might range trading suit?
Range trading may suit someone who prefers preparing defined price areas and waiting for the market to reach them. It can provide a structured way to decide where a trade is worth considering and where the idea becomes invalid. The approach requires patience while price remains in the middle of the range, followed by discipline when a boundary is tested. A trader must also be comfortable taking an exit without knowing whether the market will later return. That is especially important when the range has produced several earlier winners and begins to feel dependable. Someone who can distinguish a repeatable process from confidence built on a short winning streak may find the method easier to evaluate and follow consistently.
It may be a poor fit for someone who responds to losses by adding positions, dislikes accepting that support has failed or assumes that a market must return to a familiar price. A quiet chart can encourage larger stakes, even though the next move may be a sharp repricing. Intraday versions require attention to session changes and announcements, while multi-day versions require monitoring of overnight risk and carrying costs. Beginners can understand the basic pattern quickly, but recognising a rectangle is easier than managing a failed trade. A trader who needs predictable income or cannot tolerate a sequence of losses should not treat a range as a source of regular payments. Its boundaries are observations about past prices, not commitments about future ones.
Advantages and disadvantages of range trading
The main advantage is a clear framework for planning a trade before entering. The range helps identify an entry area, a potential destination and a location where the premise has failed. It can also provide a reason to avoid trading when price is in an unattractive part of the area. Both long and short positions are possible through spread betting, subject to contract availability and terms. A range may offer several opportunities while it remains valid, allowing the trader to study repeated applications of the same rule. These features make the approach understandable and measurable. They do not establish profitability, and a visually appealing relationship between the target and stop does not reveal how frequently either will be reached.
The disadvantages include capped room for profit, uncertain boundaries and exposure to the transition from sideways movement into a trend. Waiting for rejection can improve the evidence for an entry while leaving less distance to the target. Entering immediately at the boundary can offer better arithmetic but also buy directly into a breakdown or sell into an upward breakout. Repeated trades incur repeated costs, and one badly managed loss can erase several small gains. A market can also stop traversing the full range, leaving positions stalled well before their targets. The method therefore needs rules for time exits, shrinking opportunity and invalidation, rather than relying on the comforting idea that the price has always come back before.
Entry methods: touching the boundary or waiting for rejection
A limit entry near a range boundary prioritises the intended price. A trader might place a buy limit near support or a sell limit near resistance, accepting that the order can execute while price is still moving against the intended position. A fill is not evidence that the boundary has held. The order may also remain unfilled if the market reverses before reaching it. Check which price triggers execution and whether the chart shows that same price basis. A buy limit cannot be evaluated solely from a bid chart if the offer determines whether the purchase is available. Pending orders also need cancellation rules when a scheduled announcement approaches or the range no longer meets the original definition.
A rejection entry waits for additional behaviour, such as a completed candle returning inside the range or a move away from the boundary after a failed attempt to break it. The rule must specify what counts as confirmation and when it becomes observable. If a candle close provides the signal, execution must use a price available after that close is known. Confirmation can filter some losing entries, but it can also produce a worse price or cause the trade to be missed. Compare the remaining target distance with the stop distance after the signal. A good-looking rejection is not automatically a good trade if price has already travelled far enough into the range to remove the original advantage.
Practical example: buying near index support
Suppose a hypothetical index has an established range between approximately 8,000 and 8,100 on a bid-price chart. After testing the lower area, it moves back inside and the provider quotes 8,006/8,008. A trader buys at 8,008 for £0.50 per index point. The intended stop exit is 7,980, while the target is a closing sell price of 8,088, before the upper boundary. The 28-point stop distance gives £14 of planned price risk; the 80-point target distance gives £40 of potential price profit. The initial position would show a £1 loss if valued immediately at the unchanged bid. These are hypothetical levels, assuming the contract permits the stake and order distances, rather than a recommendation to use this setup.
If the sell price reaches 8,088 and the exit fills there, the price profit is £40. A decision to close at the range midpoint of 8,050 would instead produce £21. If the ordinary stop fills at 7,980, the price loss is £14; if a sharp break causes it to fill at 7,960, the loss becomes £24. The example assumes closure before the applicable overnight funding cut-off and no separate charges or adjustments. It uses actual opening buy and closing sell prices, so the spread is already included. The £14 planned loss is not a guaranteed maximum. The table shows alternative outcomes for the full original position, not a series of exits from the same trade.
| Alternative outcome | Actual closing sell price | Calculation at £0.50 per point | Price profit or loss |
|---|---|---|---|
| Target before upper boundary | 8,088 | (8,088 − 8,008) × £0.50 | +£40 |
| Full exit at the midpoint | 8,050 | (8,050 − 8,008) × £0.50 | +£21 |
| Stop fills as planned | 7,980 | (7,980 − 8,008) × £0.50 | −£14 |
| Downward break with stop slippage | 7,960 | (7,960 − 8,008) × £0.50 | −£24 |
The same range becomes a different proposition if the entry is late. Buying at 8,048 while retaining the 7,980 stop and 8,088 target leaves only 40 points of potential gain against 68 points of planned price risk. At £0.50 per point, those amounts are £20 and £34. The range has not changed, but the trade’s arithmetic has. A smaller stake would reduce both amounts without improving their relationship. This is why buying anywhere inside a range is not equivalent to a planned entry near its lower area. If confirmation arrives too late, the appropriate outcome under the rules may be no trade. There is no requirement to enter simply because the earlier analysis correctly identified a range.
Practical example: selling near forex resistance
Suppose EUR/GBP has been moving between approximately 0.8500 and 0.8560 on the chosen chart. After a rejection near the upper area, the provider quotes 0.8554/0.8556. The hypothetical contract defines one point as one pip, or 0.0001, and the trader sells at 0.8554 for £1 per pip. An intended stop purchase at 0.8574 gives 20 pips or £20 of planned price risk. The target is a closing purchase at 0.8508, before the lower boundary, which would produce 46 pips or £46. If an assumed net financing debit of £3 applies during the holding period, with no other adjustments, the resulting profit is £43. Actual funding depends on the contract and applicable rates, not simply on whether the position is short.
The short position closes at the offer because the trader must buy back the exposure. A bid chart touching 0.8508 does not establish that a purchase at 0.8508 was available. If resistance fails and a rapid move causes the stop purchase to fill at 0.8590, the price loss is 36 pips, or £36, before financing. This is larger than the intended £20. The example also depends on a full pip being the stake unit; fractional-pip display increments must not be confused with that definition. Confirm the point value in the contract specification and monetary preview. These mechanics remain important even when the chart analysis is correct, because the executable prices determine the account result.
Choosing targets: midpoint, opposite boundary or partial exits
The midpoint can provide a nearer objective than the opposite boundary, but a nearer target also reduces the size of a successful trade. Exiting before the far edge allows for the possibility that price turns early, without establishing that the target is likely to be reached. Choose the rule using the behaviour being tested, including obstacles inside the range, rather than assuming every bounce will cross the whole area. A target at the exact historical extreme can look attractive on paper while being difficult to execute repeatedly. The risk-reward guide explains the relationship between potential gains and planned losses. That relationship must be assessed alongside the frequency and size of actual outcomes, including exits that do not reach either planned level.
Partial exits change the result rather than providing protection without a cost. In the index example, closing half the £0.50-per-point position at 8,050 produces £10.50. If the remaining £0.25 per point exits at 8,088, it adds £20, giving £30.50 in total before any separate charges. That is less than the £40 earned by holding the full position to the same target. If the remaining half instead exits at the original 7,980 stop, it loses £7, leaving £3.50 before separate charges. The comparison shows the trade-off between securing part of a gain and retaining exposure to further movement. Any change to the remaining stop would create another set of outcomes and should form part of the tested rules.
Stop placement and recognising when the range has failed
An initial stop might sit beyond the relevant boundary, outside a defined rejection pattern or at a distance informed by recent volatility. A stop placed exactly on a widely observed line may be reached during an ordinary test, while a more distant stop increases the loss per point of stake. Neither location is automatically correct. ATR can describe recent movement, but it does not predict the largest possible gap. An ordinary stop can slip, and a stop-limit exit may remain unfilled if its price restriction cannot be met. A guaranteed stop, where available, supplies a contractual exit under its terms, with premiums and distance restrictions to check. Choose the invalidation logic before calculating the stake.
A close beyond the boundary, repeated trading outside it or a new directional structure may be reasons to stop treating the old range as valid. These are possible rules to evaluate, not universal definitions of a successful breakout. Waiting for a candle close also leaves the position exposed during that candle; an emergency price stop may therefore serve a different purpose from the analytical exit. Define how the two interact. After a stop, do not automatically reverse direction or immediately re-enter the range. Both decisions require their own conditions. Remove or amend pending orders associated with an invalid setup, because an old limit order can still execute after the market context has changed and create a position that the trader no longer intended.
Indicators for range trading
RSI and other oscillators can help describe recent movement within a range, but an overbought or oversold reading is not a promise of reversal. Such readings can persist during a trend. Bollinger Bands describe price relative to a moving average and a measure of dispersion; their boundaries move and are not automatically equivalent to fixed support and resistance. A band touch alone does not establish that a range trade is justified. A trend-strength measure may help filter conditions, but it can lag the transition the trader most wants to detect. Give each indicator a defined role and test that role. Several indicators calculated from the same prices do not provide independent guarantees that the boundary will hold.
Choosing markets, sessions and holding periods
Indices, currency pairs, shares and commodities can all form ranges, but none is permanently a range-trading market. Select an instrument whose price drivers, quote conventions and event calendar can be understood. An individual share can break its range following company news, a currency pair following an interest-rate surprise, and a commodity following supply information. Session changes also matter: a contained overnight range may be broken when a major underlying market opens. Low activity can coincide with wider spreads and poorer execution, so the quietest hours are not automatically attractive. Record the actual spread and movement during the hours you intend to trade. A pattern observed during one session should not be assumed to behave similarly during another.
The holding period changes the cost and risk of waiting for price to cross the range. Intraday positions closed before the relevant cut-off may avoid overnight funding under their terms, while multi-day trades can accumulate financing and other adjustments. The FCA’s review of CFD providers’ price and value, covering spread bets and related products, examines costs beyond the headline spread and differences in funding practices. Compare daily funded and dated contracts over the expected holding period. A forward price can incorporate financing rather than remove its economic cost. Share positions may also involve dividend or borrowing adjustments. A slow return to the intended target can therefore produce less profit than the distance on the chart initially suggests.
Position sizing and the difference between risk and margin
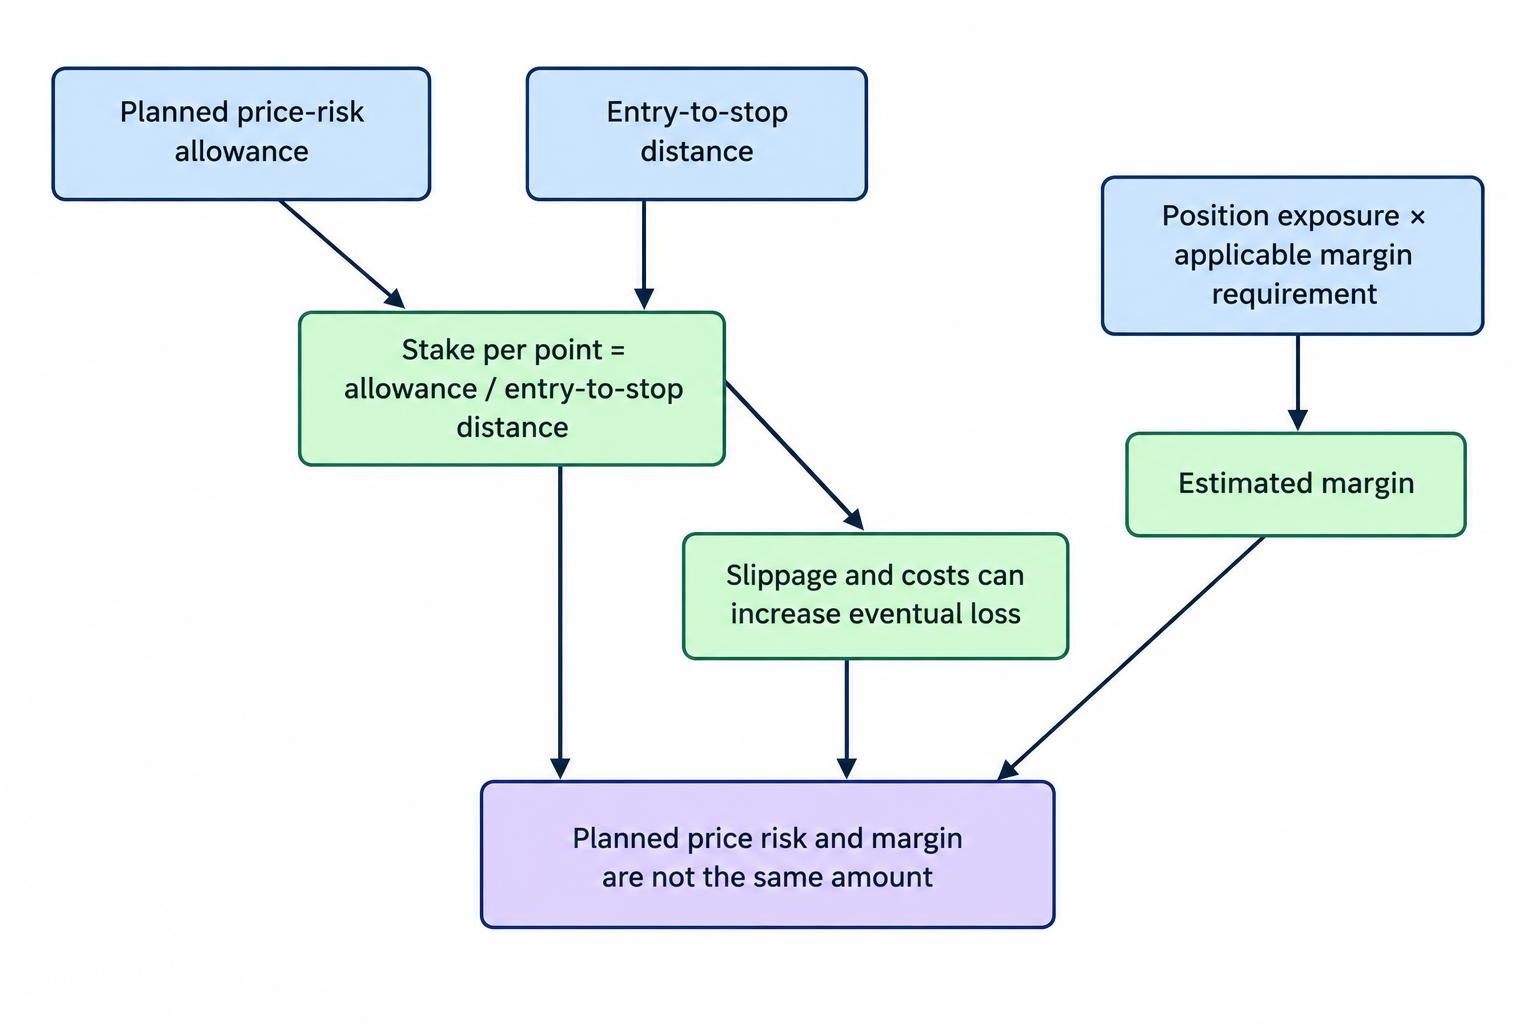
Calculate the stake from the planned price-risk allowance divided by the distance between entry and the intended stop. For example, a £20 allowance and a 40-point stop distance give £0.50 per point. If the defensible distance is 80 points, keeping the same allowance reduces the stake to £0.25 per point, assuming the contract permits it. These are arithmetic examples, not recommended allowances. Make room for expected costs and assess the effect of a worse-than-planned exit. A narrow range does not justify a large stake simply because the market has recently looked calm. The position sizing guide treats the calculation separately from the amount needed to open the trade, which is the margin requirement.
Under FCA retail rules in COBS 22.5, minimum initial margin includes 5% for major stock indices and 3.33% for major currency pairs; firms can require more. In the index example, 8,008 multiplied by £0.50 gives approximately £4,004 of exposure. An assumed 5% margin requirement would be £200.20, separate from the £14 planned price loss. The rules also provide account-level margin close-out when net equity falls below 50% of required margin, as soon as market conditions allow, and negative balance protection for relevant retail accounts. These protections do not preserve the money already in the account or guarantee an individual stop price. Available margin should therefore not determine how much exposure a range trade receives.
Repeated trades, averaging down and concentrated exposure
Several earlier bounces can make the next entry feel safer without providing evidence that it is. Repeated tests may be followed by another rejection or by a break; their number alone does not settle the outcome. Adding to a losing long as support fails, or adding to a short as resistance breaks, increases exposure precisely when the original premise is under pressure. A planned multi-entry method would need a total position limit, a common invalidation framework and testing of the entire sequence. It should not emerge as an improvised response to discomfort. Avoid treating grid or stake-doubling arrangements as ordinary range trading with extra protection. They can accumulate losses while the market continues away from the assumed boundaries.
Set a loss allowance for the sequence of attempts, not just each ticket. Three planned £20 losses around the same support area consume £60 before additional costs or slippage. Re-entering on another market should not reset the account’s loss controls, especially when the instruments respond to the same underlying factor. Several index positions or currency trades can create concentrated exposure even when each chart shows a separate range. Define when trading pauses and what evidence is required before the setup becomes valid again. The risk management guide covers these wider questions, including correlation, losing streaks and drawdown. A range strategy needs room to encounter ordinary losses without allowing repeated attempts to become an open-ended commitment to defend a price level.
How to get started with a range-trading process
Begin with one market, a defined chart interval and a written method for recognising the range. Specify the boundary zones, entry confirmation, permitted spread, stop, target and time limit, together with the events that cancel the setup. Decide how often the chart needs review and whether positions may remain open overnight. Before opening an account, follow the FCA’s guidance on checking that a firm is authorised and genuine, including its permissions and contact details. Read the contract specification, funding terms and execution policy, particularly the rules for limit orders and stop triggering. Authorisation does not establish strategy suitability or profitability. The service must also provide the order controls and position sizes needed to carry out the intended process.
Practise in a demonstration environment, recording the range as it appeared before entry rather than reconstructing it afterwards. Test placing and cancelling pending orders, attaching exits and closing a trade when the range becomes invalid. Confirm what happens to protective orders if the device disconnects and check that unwanted orders do not remain after the session. Demo fills and costs may differ from live conditions, and simulated losses do not reproduce the pressure of real ones. Progress should depend on an understandable record and knowledge of the contract, rather than a short run of profitable bounces. If a live evaluation is appropriate, a suitably small stake can help assess execution differences without assuming that the method is ready to generate regular income.
Testing a range strategy and interpreting its win rate
A fair test identifies ranges using only information available at each decision. Do not select successful historical rectangles while excluding periods when an apparent range quickly broke. Include failed boundaries, missed limit fills, spreads, slippage and relevant carrying costs. When one candle contains both the target and stop, its high and low do not reveal which was reached first. Use suitable data or conservative assumptions rather than awarding the profitable sequence automatically. Research on the probability of backtest overfitting explains why selecting among many historical rule variations can produce misleading results. Evaluate the chosen method on data not used to design it, including transitions between sideways and directional movement, rather than judging it solely during periods that were unusually favourable for ranges.
A high win rate can hide poor loss control. Suppose ten hypothetical trades produce eight price gains of £10 and two price losses of £50, all measured using actual execution prices. The win rate is 80%, but the total price result is £80 minus £100, or a £20 loss before separate charges. With those fixed outcome sizes, break-even would require approximately 83.3% winners even before additional costs. These figures do not describe a typical range strategy; they demonstrate why frequent successful bounces are insufficient evidence. Review average net wins and losses, drawdown, losses beyond the planned stop and the contribution of each range to the result. Trades made repeatedly in one favourable range are not independent evidence of reliability across changing conditions.
UK tax treatment of range-trading spread bets
HMRC’s Business Income Manual states that a person placing a spread bet is not normally carrying on a trade, with profits not taxable and losses not relieved under that normal treatment. Its guidance on spread betting exceptions explains that the contract and economic substance matter, including whether winnings arise from carrying on an existing trade. A range-trading label does not itself settle the tax position. Residence, individual circumstances and company arrangements can require separate consideration. Tax treatment should be assessed alongside the product’s costs and risks, rather than used to justify a weak method. It changes the treatment of a result, not whether the next support test will hold, and the normal absence of loss relief remains relevant.
Building a range strategy that can survive a breakout
A workable range strategy combines a boundary identified in advance with an executable entry, a realistic target and an exit that still applies when the market behaves differently from expectations. Its quality cannot be judged by the neatness of a rectangle or the number of recent winning trades. The difficult part is accepting that a familiar level can fail and that waiting for another opportunity may be preferable to defending the old one. Keep records that separate planned losses from execution problems and departures from the rules. Use those records to assess whether the method remains worthwhile after costs and changing market conditions. The objective is a process whose losses can be understood and controlled, not a belief that price must stay inside the lines.